


The Condo Deal Dies in the Building, Not the Unit
A condo buyer is buying two things. The first is Unit 5B. The second is a fractional interest in an organization responsible for the roof, the elevators, the concrete, the insurance, the reserves, the lawsuits, the maintenance schedule and potentially millions of dollars of future obligations.
The buyer gets a home inspection for the first purchase. For the second, they get a Dropbox folder. Inside might be 200 pages of budgets, reserve studies, meeting minutes, engineering reports, insurance declarations, bylaws, assessment notices, financial statements and lender questionnaires, often from different years, with inconsistent file names, duplicates and missing pages.
That messy folder quietly became one of the most important documents in American residential real estate in 2026.
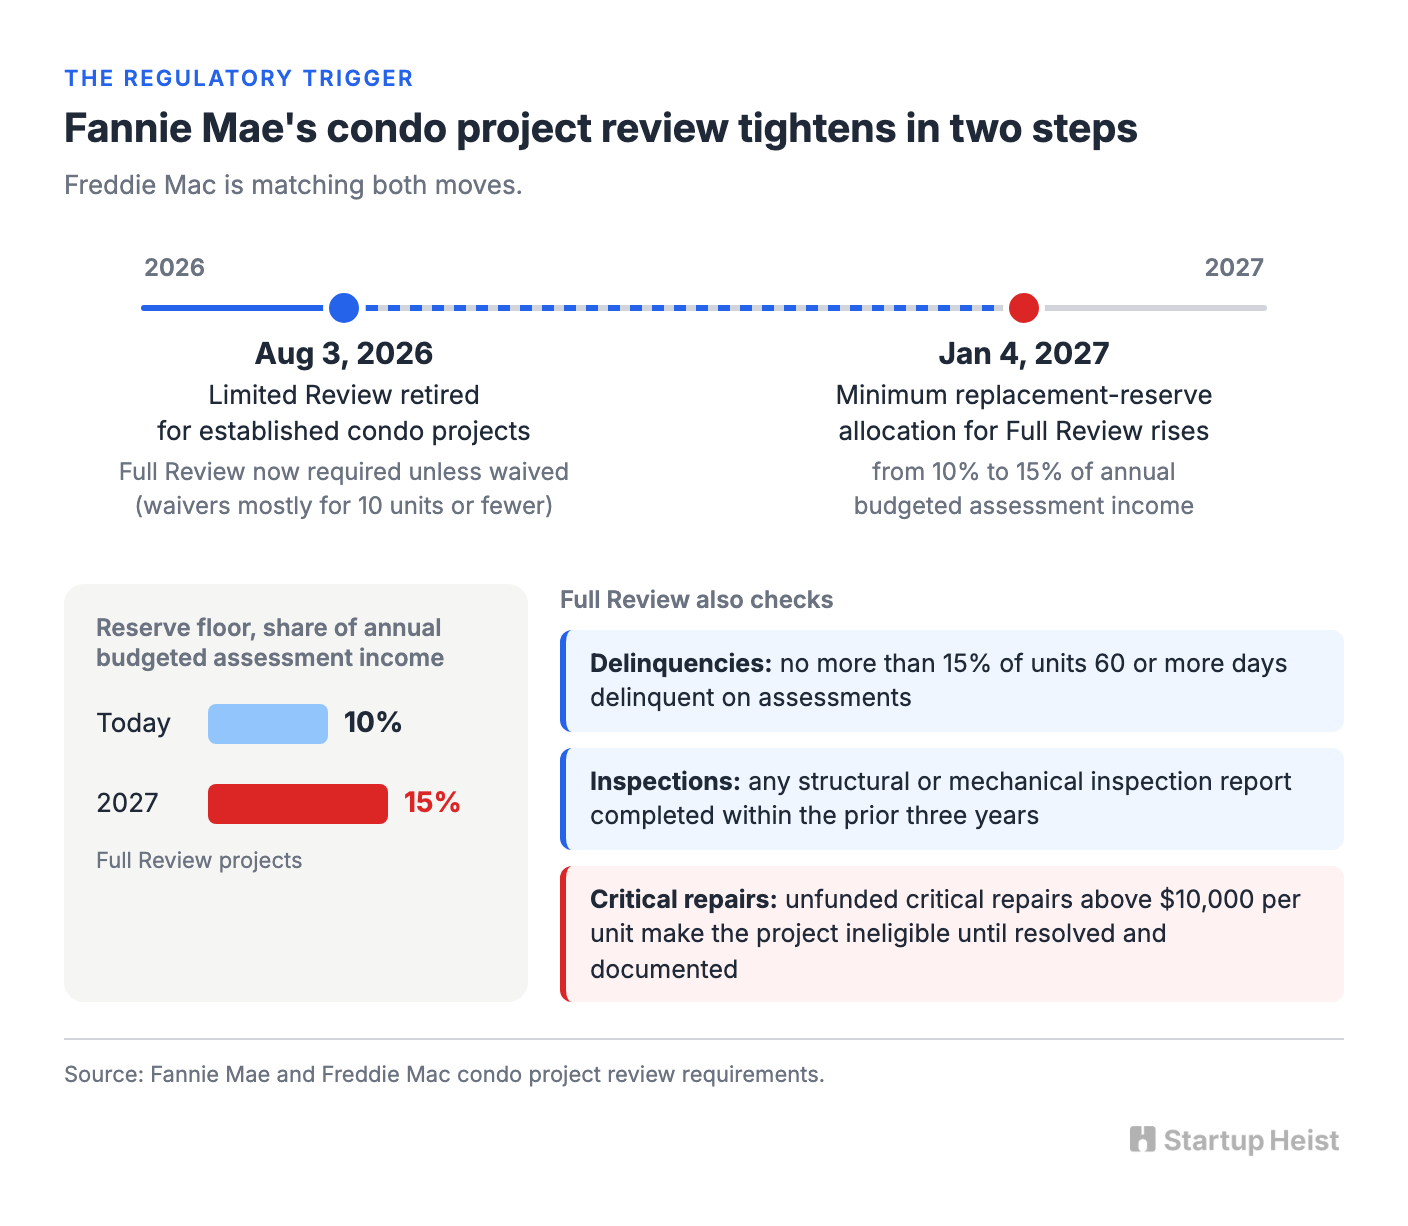
On August 3, 2026, Fannie Mae retired its Limited Review process for established condo projects. Projects that previously sailed through now need a Full Review unless they qualify for a waiver, which is mostly reserved for projects of 10 units or fewer. Beginning January 4, 2027, Fannie Mae raises its minimum replacement-reserve allocation for Full Review from 10% to 15% of annual budgeted assessment income. Freddie Mac is matching both moves.
Full Review already asks lenders to examine delinquent assessments, the association budget and replacement reserves. The broader project file can include financial statements, reserve studies, engineering reports, insurance evidence and lender condo questionnaires. And Fannie Mae is explicit about who carries the weight: the lender, not Fannie Mae and not a software vendor, is responsible for determining whether the project meets the requirements and for the accuracy of every data point entered into Condo Project Manager.
That allocation of responsibility is where the business lives. Lenders own the verdict, and they are about to need far more evidence to reach it. Nobody owns getting the evidence into shape.
That unowned job is the opportunity.
The money: Twenty condo-heavy teams at $249 to $499 a month is a $5K to $10K MRR start; 250 accounts averaging $349 is $1.05M ARR.
Inside:
• Seven-feature MVP for the transaction workspace
• Four contradiction checks that catch deal-killers
• Three-tier pricing from $49 to $499 a month
• Building memory, 90-day plan and outreach email
The product is a pre-underwriting workflow that tells agents and mortgage teams whether the condo packet is actually ready for human review, before the missing budget, the stale insurance certificate or the buried engineering report blows up the closing. It is a different product from "AI that reads HOA documents," and the difference matters more than it sounds.
The people who decide whether a condo is "safe" or "warrantable" already exist. They are underwriters, attorneys and engineers, and none of them wants a chatbot's opinion or another summary of the packet. What they want is a packet that arrives complete, current and internally consistent. Build the software that gets it there.
The New Failure Point in a Condo Transaction
Mortgage underwriting normally starts with a borrower: income, credit, debt, down payment, appraisal. A condo adds a second underwriting subject, the project itself. Fannie Mae treats condo project eligibility as a risk distinct from the borrower's credit. Financial viability, insurance, physical condition and litigation at the association level can each disqualify the mortgage.
A perfectly qualified buyer can pick a perfectly acceptable unit and still lose financing because of something happening three floors down, or something recorded in board minutes 18 months ago. Full Review requires that no more than 15% of units be 60 or more days delinquent on assessments and that the budget satisfy the reserve rules. Lenders must also review any structural or mechanical inspection report completed within the prior three years, and unfunded critical repairs above $10,000 per unit make the project ineligible until they are resolved and documented.
The market is already feeling this. MarketWatch reported on September 18, 2026 that condo owners across the country are struggling to find buyers as association fees, insurance withdrawals, special assessments and mortgage restrictions stack up. In the Miami area, the median HOA fee has climbed to $617 a month, from $401 in 2019. Condo and co-op sales ran at a seasonally adjusted annual rate of about 360,000 in August 2026, down 2.7% from a year earlier, at a median price of $371,600.
The document universe underneath those transactions is enormous. The Foundation for Community Association Research counts 373,000 U.S. community associations at the end of 2025, housing 78.1 million people and representing 35.2% of the nation's housing stock, with as many as 377,000 associations expected in 2026. Realtor.com found that 43.6% of homes listed in 2025 carried an HOA fee, up from 34.3% in 2019. Among condos and townhomes, the share was 84.8%.
Be careful with what those numbers say. Condo sales are flat to down, so nobody is riding a transaction-volume boom. The opportunity exists because every transaction is becoming more document-intensive, and the cost of a missed page just went up.
Don't Build "AI for HOA Documents"
That market already exists, and it is more crowded than the pitch decks admit.
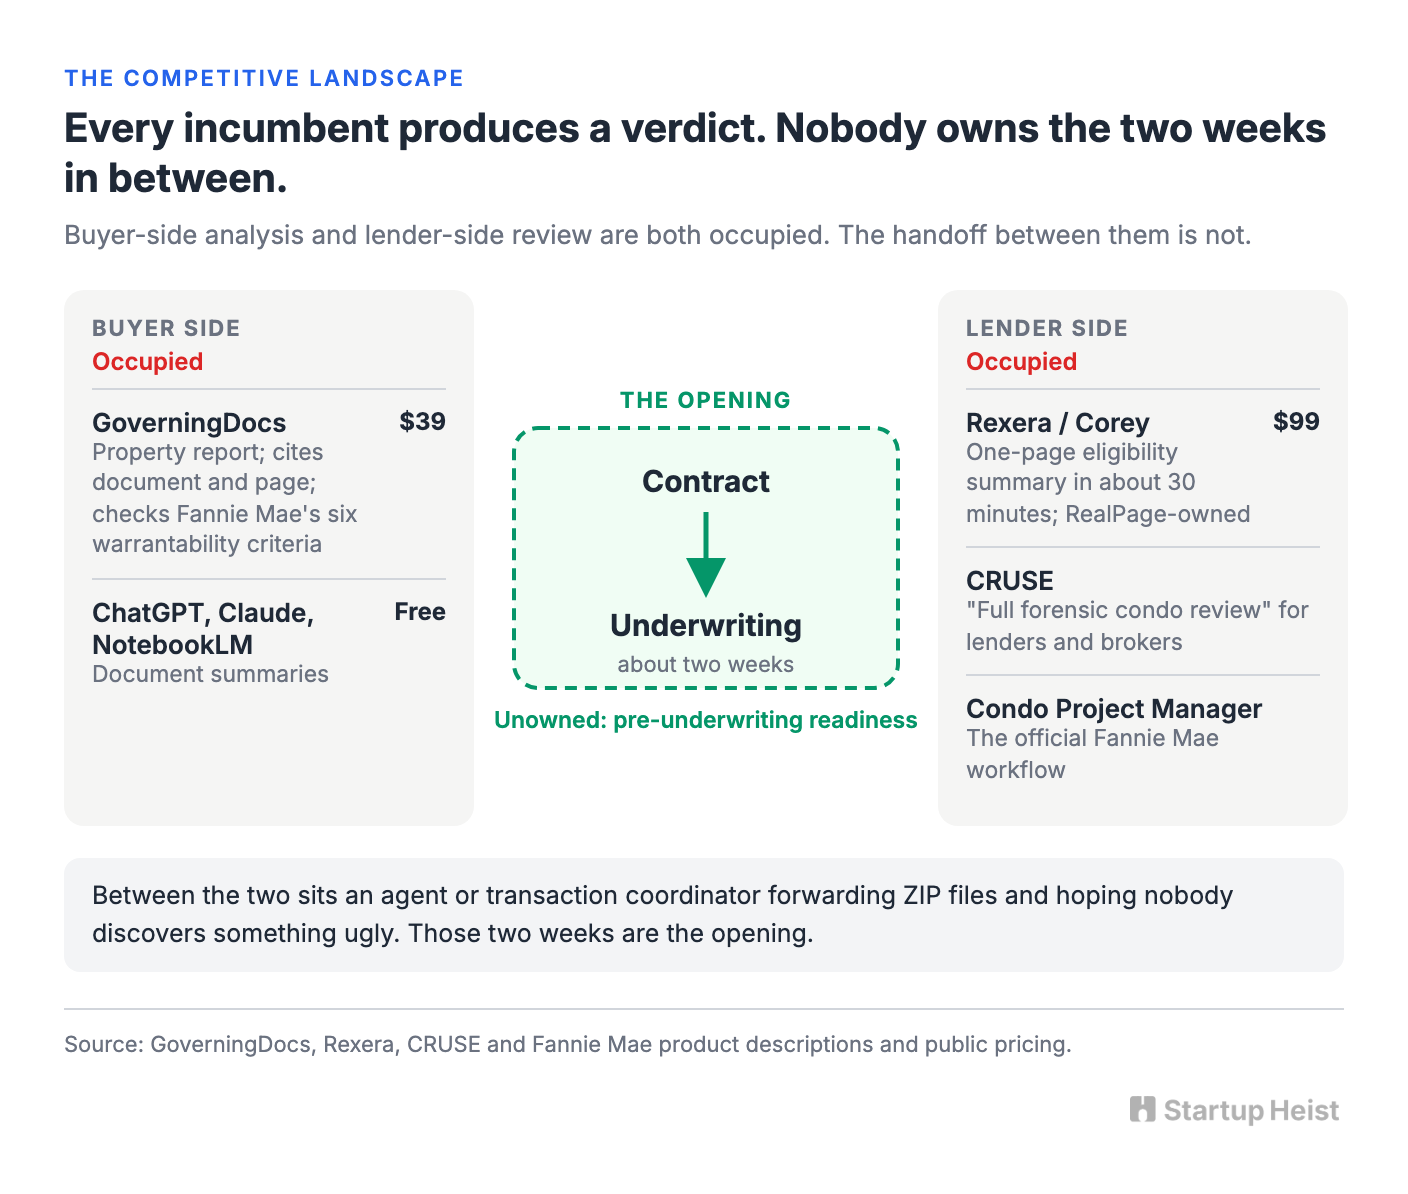
On the buyer side, GoverningDocs sells a $39 property report (first one free, no subscription) that analyzes CC&Rs, budgets, reserve studies, minutes and insurance, cites the document and page for every finding, runs the packet against Fannie Mae's six condo warrantability criteria, and markets itself to teams and brokerages. Its sample report stamps a literal "Warrantable: NO" on the property. On the lender side, Rexera, which RealPage acquired in July 2025, sells Corey, a $99 AI condo review that returns a one-page, underwriter-friendly eligibility summary against Fannie Mae, Freddie Mac and FHA standards in about 30 minutes, backed by a broader document-acquisition service. CRUSE, from Condo Review Experts, pitches "full forensic condo review" for lenders and brokers, covering questionnaires, budgets, insurance, reserve studies, litigation and engineering reports in one underwriting-grade workflow. And for anyone who just wants a summary, ChatGPT, Claude and NotebookLM are free enough.
| Need | Already served by |
|---|---|
| Buyer wants an AI HOA analysis | GoverningDocs and similar |
| Agent wants a document summary | ChatGPT, Claude, NotebookLM |
| Lender wants automated eligibility screening | Rexera/Corey, CRUSE, internal systems |
| Lender needs the official Fannie workflow | Condo Project Manager |
A generic "upload 200 pages, get a condo report" startup is late. What every player on that list shares, though, is that each one produces a verdict. None of them owns the two weeks between contract and underwriting, when an agent or transaction coordinator is forwarding ZIP files and hoping nobody discovers something ugly. Those two weeks are the opening.
The Product: Pre-Underwriting Readiness
A buyer goes under contract on a Monday. Instead of the agent emailing a folder to the loan officer and discovering gaps ten days later, the transaction coordinator drops everything they have into your workspace that afternoon.
The software never says APPROVED. What it says looks like this:
Unlock the Vault.
Join founders who spot opportunities ahead of the crowd. Actionable insights. Zero fluff.
“Intelligent, bold, minus the pretense.”
“Like discovering the cheat codes of the startup world.”
“SH is off-Broadway for founders — weird, sharp, and ahead of the curve.”


